Thomson Reserve Launch: Prices, Cash and Income Needed, With a Calculator
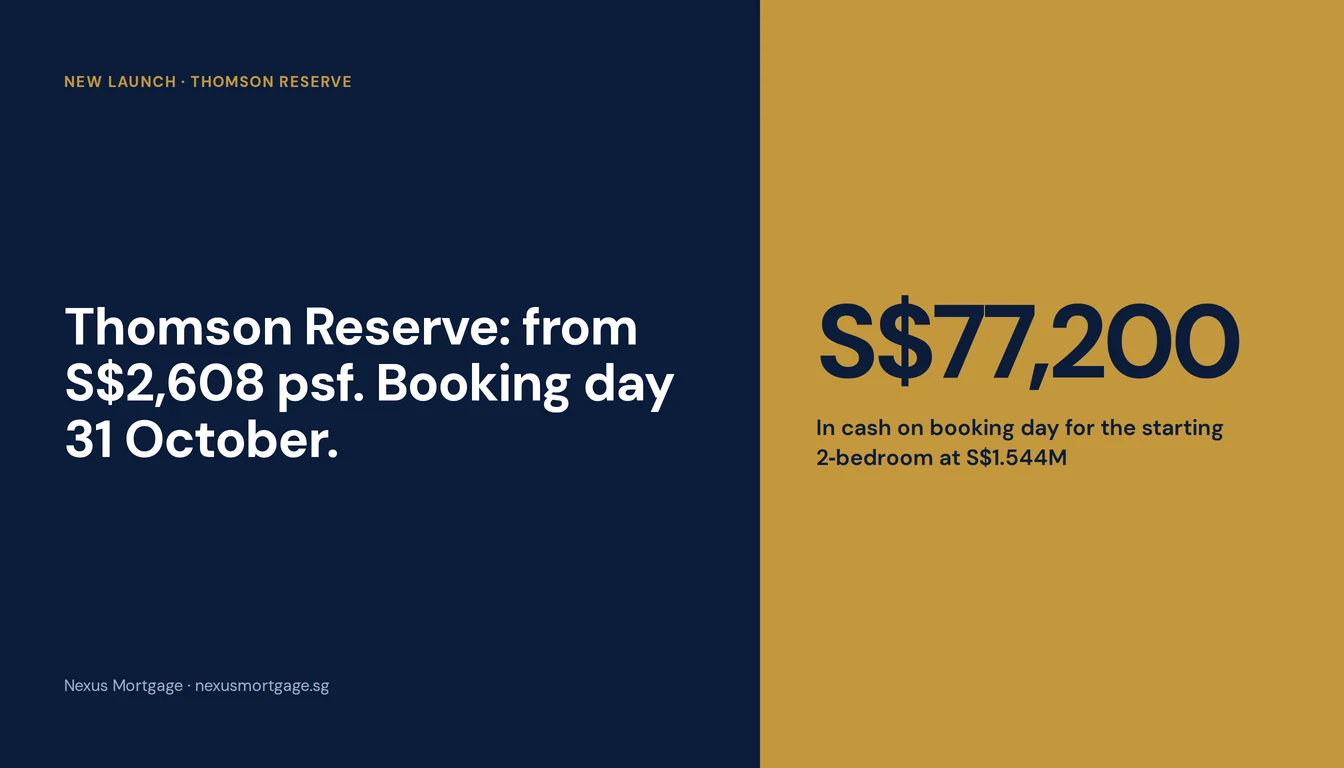
Thomson Reserve is priced from S$2,608 psf. Starting prices are S$1.544M for a two-bedroom, S$2.503M for a three-bedroom and S$3.388M for a four-bedroom. Previews opened on 17 October and booking day is 31 October 2026, with TOP expected in the second half of 2030. On the starting two-bedroom, a Singapore Citizen buying a first home needs S$77,200 in cash on booking day, about S$355,600 in cash and CPF by the S&P stage including stamp duty, and roughly S$10,050 a month in income to pass the bank's stress test. Use the calculator below for your own unit and profile.
We first wrote about Thomson Reserve in July, when it was still a pre-launch with no price. The developers have now published their launch details, so this guide is rewritten around the real numbers. It is about the financing side: what each unit type costs to buy, what the bank will lend, and what has to be in place before you book. It is not a recommendation to buy, and we are not the developer's sales team.
The Launch Facts
Everything in this table comes from the developers' launch release and factsheet of 15 October 2026.
| Developer | Tamarind Development Pte. Ltd. (CapitaLand Development, UOL Group and Singapore Land Group) |
| Address | 1 to 11 Bright Hill Drive, District 20 (former Thomson View) |
| Tenure | 99 years from 14 July 2026 |
| Units | 1,268, in four 21-storey towers (Classic Collection, 740 units) and two 30-storey towers (Luxury Collection, 528 units) |
| Site | 51,567 sqm, plot ratio 2.1; towers cover 12% of the site |
| Transport | Sheltered link to Upper Thomson MRT (Thomson-East Coast Line); Bright Hill interchange with the Cross Island Line one stop away |
| Previews | From 17 October 2026 |
| Booking day | 31 October 2026 |
| Expected TOP | Second half of 2030 |
| Expected vacant possession | 28 February 2031 |
Interest is high. The Edge Singapore reported 11,800 visitors on the first weekend of the public preview. Visitors are not buyers, but a crowded launch means the better stacks go early, so it pays to have your financing settled before you walk in rather than after.
Prices and Unit Mix
The developers have published three starting prices. Each is the cheapest unit of its type, so most units will cost more.
| Unit type | Size | From | Works out to |
|---|---|---|---|
| 2-Bedroom | 592 sq ft | S$1.544M | S$2,608 psf |
| 3-Bedroom | 947 sq ft | S$2.503M | S$2,643 psf |
| 4-Bedroom | 1,238 sq ft | S$3.388M | S$2,737 psf |
The unit mix leans heavily to two-bedders: 716 of the 1,268 units are two-bedroom layouts of some kind.
| Layout | Units | Size |
|---|---|---|
| 2-Bedroom | 100 | 592 sq ft |
| 2-Bedroom Premium | 416 | 678 sq ft |
| 2-Bedroom Premium + Study | 200 | 732 and 775 sq ft |
| 3-Bedroom | 120 | 947 sq ft |
| 3-Bedroom Premium | 170 | 1,055 sq ft |
| 3-Bedroom Premium + Study | 60 | 1,152 sq ft |
| 4-Bedroom | 90 | 1,238 sq ft |
| 4-Bedroom Premium (private lift) | 56 | 1,367 sq ft |
| 4-Bedroom Premium + Study (private lift) | 28 | 1,485 sq ft |
| 5-Bedroom Suite (private lift) | 28 | 1,808 sq ft |
Only 100 units are the 592 sq ft two-bedroom that sets the S$1.544M headline. If you are budgeting for a two-bedroom, run the calculator at the price of the layout you actually want, and expect the Premium layouts and higher floors to sit above the starting figure.
Thomson Reserve Calculator
Pick a unit type or enter the price from the price list, then set your profile. It shows the cash and CPF due at each stage, the stamp duty, the loan the bank can give, and the income you need to pass the stress test.
The loan
What you pay before the bank lends
Can you pass the stress test?
Monthly instalment as the building goes up
| Stage | Loan drawn | Est. monthly |
|---|
Estimate only, for planning. Stamp duty uses IRAS residential rates; ABSD shown is for an individual buyer, and couples buying jointly pay at the higher profile. LTV assumes the tenure ends by age 65 and is no longer than 30 years; a longer tenure lowers the LTV. Instalments are principal and interest on the amount drawn, over the full tenure. The default rate is indicative only: it uses 3M SORA plus 0.20%, a spread several banks offered on loans above S$1M for uncompleted properties in mid-2026. Packages change, so confirm with the bank. Not an offer of credit.
Cash and Stamp Duty by Unit Type
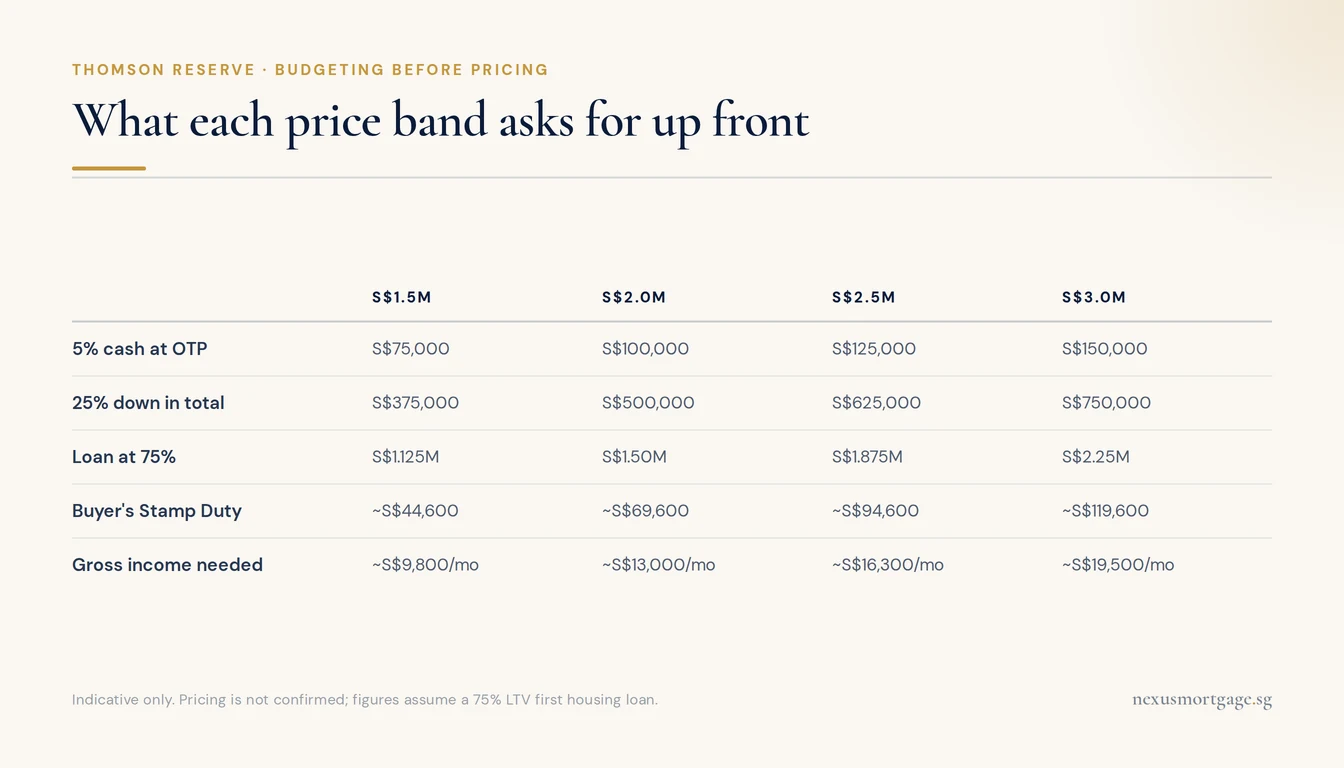
The 5% booking fee is the only part that must be cash on the day. The stress test decides the rest.
A new launch is paid in stages under the progressive payment scheme. The first 20% comes from you before the bank lends anything:
- 5% booking fee when you take the option to purchase on booking day. This part must be cash.
- 15% within eight weeks of the option date, when you exercise the sale and purchase agreement. Cash, CPF, or both.
- Buyer's Stamp Duty within 14 days of the S&P, and ABSD in the same window if it applies.
On a first housing loan at 75% LTV, the remaining 5% of the downpayment is collected at the first construction stage, and the bank starts paying the developer after that. For a Singapore Citizen buying a first property, the starting price of each type works out like this:
| 2-Bedroom | 3-Bedroom | 4-Bedroom | |
|---|---|---|---|
| Starting price | S$1,544,000 | S$2,503,000 | S$3,388,000 |
| Booking fee, 5% cash | S$77,200 | S$125,150 | S$169,400 |
| At S&P, 15% cash or CPF | S$231,600 | S$375,450 | S$508,200 |
| Buyer's Stamp Duty | S$46,800 | S$94,750 | S$142,880 |
| Total by the S&P stage | S$355,600 | S$595,350 | S$820,480 |
| Loan at 75% | S$1,158,000 | S$1,877,250 | S$2,541,000 |
ABSD comes on top for anyone who is not a Singapore Citizen buying a first home. On the same three starting prices it is S$308,800, S$500,600 and S$677,600 for a Citizen's second property at 20%, and S$77,200, S$125,150 and S$169,400 for a PR's first property at 5%. Plan for ABSD in cash: IRAS expects it within 14 days, and paying it from CPF depends on your CPF balance and the CPF Board's rules, often by claiming it back afterwards.
The Income Each Unit Needs
The bank does not test you at the rate you will pay. MAS requires it to work out your instalment at the higher of your actual rate and 4% a year, then check that all your monthly debt repayments, including this one, stay within 55% of gross income. That is the TDSR limit, and it decides more purchases than the price does.
| 2-Bedroom | 3-Bedroom | 4-Bedroom | |
|---|---|---|---|
| Loan at 75% | S$1,158,000 | S$1,877,250 | S$2,541,000 |
| Stress-test instalment (4%, 30 years) | S$5,528 | S$8,962 | S$12,131 |
| Gross income needed per month | S$10,052 | S$16,295 | S$22,057 |
Those figures assume no other debts and a 30-year tenure. Two things push them up. Any car loan, card balance or personal loan instalment comes off the same 55%. And the tenure must end by age 65 to keep the 75% LTV, so a borrower aged 40 gets 25 years, not 30, and a higher instalment on the same loan. The calculator handles both.
“The stress test, not the price list, is usually what decides which unit you can book. Know your number before preview day, not on it.”
HDB Upgraders: ABSD and the Second Loan
Thomson Reserve will draw a lot of HDB upgraders, and they face two separate issues that are easy to mix up.
ABSD. If you keep your flat while you buy, Thomson Reserve is your second residential property. A Singapore Citizen pays 20% ABSD: S$308,800 on the starting two-bedroom. A married couple with at least one Singapore Citizen who buy jointly can claim it back if they sell the flat within six months of Thomson Reserve's TOP or CSC, whichever is earlier. TOP is expected in the second half of 2030, so that is a long runway, but you still need the ABSD in hand at the S&P stage. Check your eligibility against IRAS's conditions before you book.
The second loan. ABSD is about how many properties you own. The loan limit is about how many housing loans you still owe. If your HDB flat still has a loan, HDB or bank, the Thomson Reserve loan is a second housing loan: the maximum LTV drops from 75% to 45%, and at least 25% of the price must be cash. On the S$1.544M two-bedroom that means a loan of S$694,800 and at least S$386,000 in cash, before stamp duty. Clearing the HDB loan before you book changes that completely, which is why the order of steps matters. Our HDB-to-condo upgrade guide walks through the sequencing.
Progressive Payments to 2031
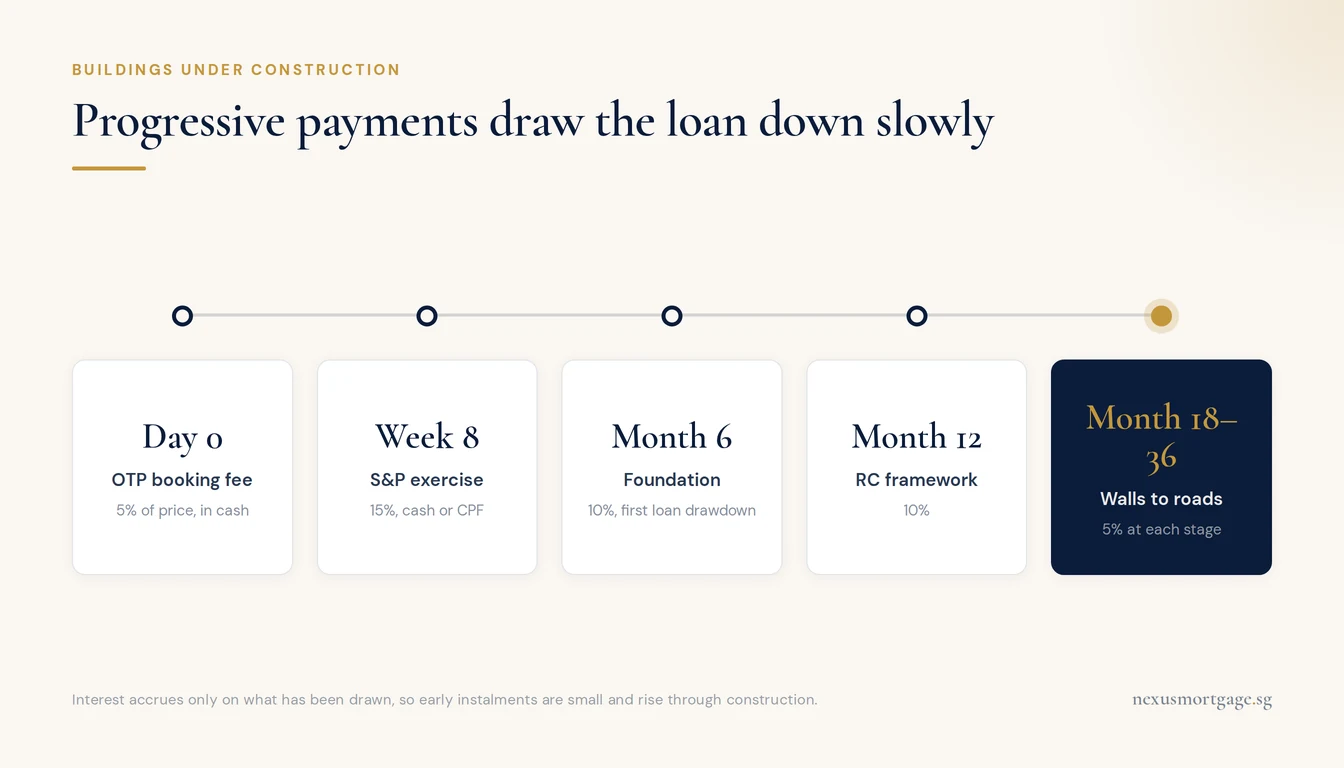
Instalments start small and step up sharply at TOP, when a quarter of the price is drawn at once.
Under the progressive payment scheme the bank pays the developer stage by stage as the building goes up, and you pay interest only on what has been drawn. Instalments start small and rise towards TOP. On the S$1.544M two-bedroom with a 75% loan, at an illustrative 1.44% over 30 years:
| Stage | Of price | Loan drawn | Monthly |
|---|---|---|---|
| Booking and S&P | 20% | none | none |
| Foundation | 10% | S$77,200 | about S$264 |
| Reinforced concrete | 10% | S$231,600 | about S$793 |
| Walls, ceiling, doors and windows, car park and roads | 5% each | up to S$540,400 | up to about S$1,850 |
| TOP, expected 2H 2030 | 25% | S$926,400 | about S$3,171 |
| CSC | 15% | S$1,158,000 | about S$3,963 |
The 1.44% is 3M SORA of 1.24% on 15 October 2026 plus a 0.20% spread, which is what several banks offered on loans above S$1M for uncompleted properties in mid-2026. It is an illustration, not a quote, and SORA will move before 2030. What does not change is the shape: the large step comes at TOP, when 25% of the price is drawn at once. That is also when an upgrader typically needs to sell the HDB flat. See our new launch financing guide for how the stages work in general.
The Rate During Construction
Loans for uncompleted properties are almost always floating, priced off SORA or a bank's own board rate. Fixed packages are generally sold on completed homes. So for Thomson Reserve the decision until 2030 is not fixed or floating; it is which floating package, and on what terms:
- The spread and how it steps up. A low first-year spread that jumps in year three matters less here, because the drawn balance is small in the early years.
- The lock-in. Ideally it ends before TOP, so you are free to reprice or refinance when the full loan is drawn and fixed packages become available.
- Valuation. New launches are valued off the developer's own pricing, and banks do not all value the same unit the same way. A lower valuation means a smaller loan and more cash from you.
Our fixed vs floating guide covers the choice you will face at TOP, and today's SORA is on our rates page.
Before Booking Day
- Get an In-Principle Approval for the loan size you need, ideally from more than one bank. It confirms your TDSR and loan limit before you commit the booking fee. See how an IPA works.
- Have the 5% ready in cash, usually as a cashier's order, for the unit price you are aiming at, plus some headroom for a higher floor.
- Check your CPF Ordinary Account balance and how much of the next 15% and the stamp duty it can cover. Private property has CPF usage limits tied to valuation and remaining lease.
- If you own an HDB flat, decide now whether you will sell before or after TOP, and whether any HDB loan will be cleared first. That decides your LTV and your ABSD.
- Put any car loan or card debt into the sums. Every dollar of monthly debt reduces the loan you can get.
- Know your walk-away price. Set it from the calculator before the preview, not at the sales table.
If you want a second pair of eyes on the numbers, get in touch. We compare packages across the banks for new launches at no cost to you.
Frequently Asked Questions
From S$2,608 psf. Starting prices are S$1.544M for a 592 sq ft two-bedroom, S$2.503M for a 947 sq ft three-bedroom and S$3.388M for a 1,238 sq ft four-bedroom. Those are the cheapest units of each type; the full list is out for booking day on 31 October 2026.
Previews began on 17 October 2026 and booking day is 31 October 2026. TOP is expected in the second half of 2030, with vacant possession expected by 28 February 2031.
At S$1.544M with a 75% loan over 30 years, the bank's 4% stress test gives an instalment of about S$5,528 a month, which needs about S$10,052 of gross monthly income under the 55% TDSR, before other debts.
The 5% booking fee in cash: S$77,200 on the starting two-bedroom. A further 15% follows within eight weeks in cash or CPF, plus stamp duty within 14 days of the S&P. For a Citizen's first home that is about S$355,600 by the S&P stage.
Yes, once the flat has met its MOP. Expect 20% ABSD as a Citizen buying a second property, refundable to eligible married couples who sell the flat within six months of TOP or CSC. If the flat still has a loan, the new loan is capped at 45% LTV with at least 25% in cash.
Not usually during construction. Loans for uncompleted properties are generally floating. Fixed packages become available on completed homes, so the time to switch is around TOP.
Tamarind Development Pte. Ltd., a joint venture of CapitaLand Development, UOL Group and Singapore Land Group, redeveloping the former Thomson View.
Further reading
- New launch financing: how progressive payments and BUC loans work
- HDB to condo upgrade: selling and buying in the right order
- The MAS 4% stress test: why the bank tests you at a higher rate
- Second property loan LTV: why an outstanding HDB loan caps you at 45%
- Stamp duty guide: BSD and ABSD in full
This article is general information on financing a purchase at Thomson Reserve. It is not financial, legal or tax advice, not a recommendation to buy, and not an offer of credit. Nexus Mortgage is not connected to the developer. Prices are the developers' published starting prices; actual unit prices are set by the price list on booking day. Loan, stamp duty and income figures assume the price shown, a first housing loan at 75% LTV over 30 years, no other debts and the 4% residential stress rate, unless stated. Instalments during construction are illustrative and use an assumed rate. LTV, TDSR, ABSD and CPF rules are set by MAS, IRAS and the CPF Board and may change; confirm them for your circumstances. Current as at 19 October 2026. Sources: UOL Group and CapitaLand Development launch release and factsheet, 15 October 2026, The Edge Singapore: preview attendance, IRAS: Buyer's Stamp Duty, MAS Notice 632.
About the author — Dan Ler has advised on Singapore home loans since 2017 at Nexus Mortgage SG, an independent brokerage comparing 16+ MAS-regulated lenders. Nexus has facilitated 500+ home loans across HDB, EC, private condo and landed property segments. Banks pay Nexus on disbursement, so there is no cost to the borrower.